A senior accountant resume should show how you review evidence, coordinate close dependencies, work through accounting questions and help other preparers improve. This complete fictional example makes those responsibilities visible while keeping controller approval, policy decisions and final reporting authority clear.
These previews use the same layouts as the builder, with identical example content. Open a full preview to inspect the text and spacing.
Fictional candidate, employers, education and results. The optional portrait is AI-generated. Use your own evidence and photo; the example is not inserted into your resume.
Ledger
A centered serif header and gold contact rule lead into a single-column record of review work and career progression.
Before sending: Long review bullets still need concise subjects and clear approval boundaries. Check that the final controller limitation stays with its project on later pages.
The plain left header and restrained section headings keep preparation-to-review progression in one main sequence.
Before sending: Its quiet styling leaves seniority to the evidence. Repeating the word led cannot replace a reviewer, decision or named close workstream.
Colored headings, small square markers and a date gutter organize the same single-column work history.
Before sending: The date gutter and markers change line wrapping. Confirm both earlier staff dates and the complete research memo description in the export.
“Use” opens signup with that design and photo preference selected for the builder. A free account is required. Free-plan PDF downloads include a watermark; see current plans for paid options. Photo conventions vary; follow the employer’s instructions and local expectations.
Ledger, Essential and Signal use Daniel’s same complete record. Each offers a photo-off default and an optional photo preview. Read every exported page and the full text below before choosing. The signup buttons carry the selected design and photo preference into the builder; the fictional work history and portrait are not inserted into your account.
Ledger introduces the record with a centered serif header and gold contact rule. Essential uses a plain left header; Signal adds colored section headings and square markers. All three keep the main work history in a single-column sequence. Choose a layout that preserves your review scope and career progression at normal reading size.
A complete senior accountant resume example
Daniel Rivera is a fictional senior accountant at a regional equipment distributor in Charlotte, North Carolina. He coordinates an assigned operating-expense close workstream, reviews staff-prepared reconciliations and recommends treatment for controller approval. Every person, employer, qualification and result is invented; example.com destinations are fictional placeholders. The portrait is AI-generated. This guide uses AI-assisted research and drafting.
Senior accountant at a regional equipment distributor, with prior staff accounting experience. Reviews assigned reconciliations, coordinates operating-expense close dependencies and documents recommendations for controller approval. Coaches two staff preparers on supporting explanations while keeping final sign-off, policy approval and external reporting with the controller.
Skills
Reconciliation review · Close workstream planning · Accounting research support · Variance commentary · Staff coaching · Excel analysis · Review documentation
Experience
Senior Accountant
Alderfield Equipment Supply · Charlotte, NC
February 2024–Present
Reviewed 26 assigned balance-sheet reconciliations prepared by two staff accountants for each January–June 2026 close, returned unsupported items with review notes and escalated unresolved balances to the controller.
Coordinated the assigned operating-expense close workstream; its controller-ready pack was submitted on business day six in January 2026 and day five in February–June, with controller sign-off tracked separately.
Investigated an unusual equipment-service invoice, documented the contract terms and proposed treatment under the existing accounting policy, then submitted the memo and proposed entry for controller approval.
Coached two staff accountants on linking support and writing reconciling-item explanations; in a June 2026 check of their 26 assigned reconciliations, 23 arrived with the required references and three were returned for completion.
Staff Accountant
Pinehaven Commercial Products · Charlotte, NC
July 2020–January 2024
Prepared cash, prepaid and accrued-expense reconciliations for assigned accounts at the April–December 2022 closes, recording explanations and supporting references for the senior accountant’s review.
Prepared the September 2023 operating-expense variance bridge explaining a $90,000 increase from August; separated timing items from changes in activity and sent unresolved explanations to the accounting manager.
Education
Bachelor of Science in Accounting · Fairhaven College · Charlotte, NC
Mapped the support needed from purchasing and staff preparers before the assigned operating-expense pack could reach the controller. Logged the controller-ready submission separately from final sign-off. The pack moved from business day six in January to day five in each February–June close; changes in workload and upstream support were not isolated, so the record does not attribute the timing difference solely to this project. Controller approval remained required.
The earlier staff job establishes preparation experience; the current job adds review, workstream coordination and coaching. Daniel is not presented as the controller, a formal people manager or an independent auditor. No CPA license or certification is claimed. The record is an example of resume evidence and does not establish that a candidate meets every senior vacancy’s requirements.
Make the review decision visible
For senior work, explain what happened after someone prepared the support. Did you compare it with the ledger, question an unsupported explanation, identify a missing dependency, return work for completion or escalate a proposed treatment? Name the scope you reviewed and the person who retained the next decision. A sentence about your own recurring entries may be relevant, but it does not by itself demonstrate review of another preparer’s work.
Daniel’s reconciliation bullet identifies two staff preparers, 26 assigned accounts at each close and escalation to the controller. His research example describes an unusual invoice, a memo and a recommendation under existing policy. It stops at submission for approval. That is useful evidence of judgment without claiming that he set policy, signed financial statements or issued an audit opinion. Keep transaction details at a level your employer permits you to disclose.
Describe coaching separately from formal management. Reviewing two colleagues’ work and teaching a support checklist does not establish authority over hiring, performance ratings or compensation. If you really held those responsibilities, state them with the actual team relationship. Otherwise, precise phrases such as coached two staff preparers or reviewed analyst support tell the reader more than an inflated “managed the finance team.”
The current employer examples have overlapping but different scope. Philz explicitly includes review of junior support and staff development. Oscar combines initial analyst review with hands-on close execution under an accounting manager. Vercel emphasizes assigned operational areas, analysis and cross-team improvements. These selected roles illustrate why preparation and review can coexist in senior work. They do not establish a universal years-of-experience threshold, industry requirement or authority level.
Six annotated senior accountant bullet rewrites
Each after sentence is part of the full base resume. Check the same distinctions in your own record: review versus preparation, recommendation versus approval, a workstream versus the company close, and an explained variance versus a saving.
Review ownership rather than a larger preparation count
Before: Oversaw all accounts and guaranteed accurate financial statements.
After: Reviewed 26 assigned balance-sheet reconciliations prepared by two staff accountants for each January–June 2026 close, returned unsupported items with review notes and escalated unresolved balances to the controller.
Why it works: Names the preparers, recurring scope and escalation path. Twenty-six reconciliations over six closes represents 156 account-month reviews, not 156 unique accounts or assurance over the company’s financial statements.
Evidence to check: Assigned review list, preparer names, dated comments and controller escalation log.
Close timing with a fixed finish point
Before: Single-handedly cut the company close by 50%.
After: Coordinated the assigned operating-expense close workstream; its controller-ready pack was submitted on business day six in January 2026 and day five in February–June, with controller sign-off tracked separately.
Why it works: The one-business-day change is five versus six, or about 16.7% of the January elapsed business-day count. It describes one workstream and an observed sequence; it does not establish company-wide acceleration or sole causation.
Evidence to check: Same workstream checklist, submission timestamps, business-day calendar and separate sign-off timestamps.
Judgment proposed within approval limits
Before: Set accounting policy and independently approved complex treatments.
After: Investigated an unusual equipment-service invoice, documented the contract terms and proposed treatment under the existing accounting policy, then submitted the memo and proposed entry for controller approval.
Why it works: Makes research and recommendation visible without inventing policy-setting authority. The resume describes the work; it does not teach a reader how that transaction should be accounted for.
Evidence to check: Research memo, policy reference, versioned proposed entry and controller decision.
Mentoring with an observable review result
Before: Managed an elite team and eliminated rework.
After: Coached two staff accountants on linking support and writing reconciling-item explanations; in a June 2026 check of their 26 assigned reconciliations, 23 arrived with the required references and three were returned for completion.
Why it works: Twenty-three plus three reconciles to 26. This is a single review snapshot of document completeness, not an error-free accounting rate or proof that coaching alone caused the result. Coaching does not imply line-management responsibility.
Evidence to check: Coaching agenda, defined reference checklist and complete June review register.
Earlier preparation experience that supports progression
Before: Led financial controls from the start of my career.
After: Prepared cash, prepaid and accrued-expense reconciliations for assigned accounts at the April–December 2022 closes, recording explanations and supporting references for the senior accountant’s review.
Why it works: Keeps the earlier staff title and preparation responsibilities intact. A promotion story is stronger when it shows what changed rather than retroactively granting the earlier role senior authority.
Evidence to check: Staff assignment records, dated workpapers and senior review notes.
Reporting support without a savings claim
Before: Saved the business $90K through financial analysis.
After: Prepared the September 2023 operating-expense variance bridge explaining a $90,000 increase from August; separated timing items from changes in activity and sent unresolved explanations to the accounting manager.
Why it works: An explained expense increase is neither a saving nor a cash recovery. The comparison months and escalation limit make the contribution assessable without turning an analysis into a financial outcome.
Evidence to check: August and September reports on the same basis, bridge calculations and manager review comments.
Define what the close metric actually measures
Choose the finish point before comparing time. A prepared pack, a reviewer-ready pack, controller sign-off and a locked period are different milestones. Daniel’s operating-expense pack reached controller-ready status on business day six in January and day five in the following five closes. The company’s final close date is not provided. Calling that a one-day company close reduction would change the measure.
Five versus six business days is a one-day difference, approximately 16.7% of January’s six-day count. It is not a 50% reduction. More importantly, an observed sequence does not isolate why timing changed. Upstream support, workloads and other colleagues may have contributed. The project therefore records the submission dates and keeps sign-off separate without attributing the entire difference to Daniel.
Use the same discipline for review counts. Twenty-six assigned accounts across six months means 156 account-month reviews. In the June document check, 23 packs had the required references and three were returned; 23 plus three equals 26. That is evidence about reference completeness at one point in time. It does not establish an accounting accuracy rate, control effectiveness or an absence of future issues.
The $90,000 expense increase belongs to an earlier staff analysis comparing September with August 2023. An explanation of a movement is useful work even when it does not reduce spending. If you claim a saving, identify the actual comparison, measurement period, shared ownership and evidence that the amount was realized. Do not turn an analysis, adjustment or budget variance into cash saved.
Support senior accounting skills with decisions
Target the vacancy through examples of work you can defend. A systems migration, technical topic or control framework belongs on your resume only if you can explain your part and review limits. The sample names Excel and review documentation; it does not invent NetSuite, Workday, SOX ownership or SEC reporting experience just because a cited employer mentions related work.
Senior accountant skills, evidence and fictional examples
Skill
Evidence to gather
Fictional example
Reconciliation review
Scope reviewed, preparer relationship and unresolved items.
Twenty-six assigned accounts prepared by two staff accountants.
Close planning
Dependencies, a stable finish point and separate approval dates.
Operating-expense pack submission tracked before controller sign-off.
Accounting research support
The question, sources considered and decision owner.
A recommendation under existing policy submitted to the controller.
Coaching
What you taught and how the work was reviewed.
Reference-writing guidance and a 26-reconciliation completeness check.
Variance analysis
Comparable periods, a reconciled bridge and open questions.
A $90,000 September-versus-August expense increase explained for review.
Excel and documentation
The actual analysis, checks and reviewer use.
A close dependency register rather than an unsupported automation claim.
In the summary, pair the role and business setting with these responsibilities. Under each job, make the progression explicit rather than repeating an identical list of close tasks. Daniel’s staff role prepares support for review; the later senior role reviews other preparers and coordinates dependencies. Preserve that distinction even when both employers used similar systems.
Keep degrees, credentials and authority separate
Use the exact degree, field, institution and dates you earned. Daniel’s fictional degree is complete and no certification is listed. A senior title does not itself establish CPA licensure or authority to provide an audit opinion. BLS provides broad occupational context; the target employer and relevant jurisdiction determine which qualifications matter for the particular application.
The selected postings also differ. Vercel lists a degree requirement with CPA preferred. Philz requests a degree and expresses a strong CPA preference; its wording about a credential in progress should not be copied as though it were an issued license. Oscar lists degree-or-experience criteria and CPA licensure among bonus qualifications. Check the live vacancy. If you have exam progress, training or an active license, describe that actual status precisely; examination completion alone does not establish licensure.
Moving from staff preparation toward senior work
If you are applying for your first senior role, look for work that already shows a broader decision: covering a reviewer, coordinating an assigned dependency, investigating a nonroutine question or helping a colleague improve support. State the duration and actual authority. Do not promote yourself on paper by changing a staff title or converting occasional coverage into permanent team leadership.
Fictional first-senior-role adaptation
Summary: Staff accountant seeking a senior role after recurring close preparation and temporary review coverage. Documents reconciling-item questions, coordinates missing support and sends unresolved recommendations to the accounting manager.
Experience bullet: During the reviewer’s two-week absence, checked support references for eight assigned reconciliations prepared by a colleague, recorded questions and sent the pack to the manager for final review.
This short coverage example is separate editorial fiction, not an extra job or claim in Daniel’s resume. Use only coverage you actually performed. If your experience is entirely preparation, present it clearly and target roles whose requirements fit. A senior heading cannot replace the review or judgment evidence an employer requests; the staff accountant guide provides a preparation-focused comparison.
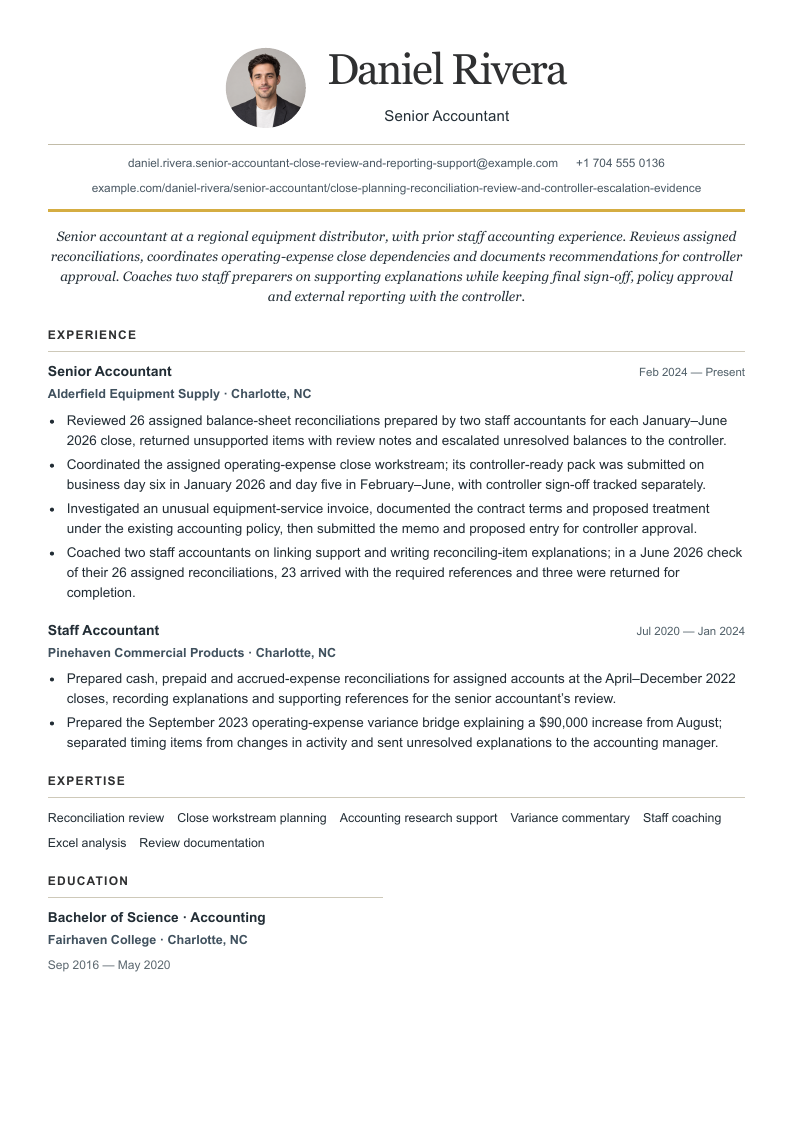
Read the long-contact version with the photo on
The Ledger long-contact scenario changes only Daniel’s resume email and portfolio URL. Work history, education, skills and project content match the base example. The optional photo changes the header composition; check the complete contact strings against the text below, including their final characters and linked destinations.
Senior accountant at a regional equipment distributor, with prior staff accounting experience. Reviews assigned reconciliations, coordinates operating-expense close dependencies and documents recommendations for controller approval. Coaches two staff preparers on supporting explanations while keeping final sign-off, policy approval and external reporting with the controller.
Skills
Reconciliation review · Close workstream planning · Accounting research support · Variance commentary · Staff coaching · Excel analysis · Review documentation
Experience
Senior Accountant
Alderfield Equipment Supply · Charlotte, NC
February 2024–Present
Reviewed 26 assigned balance-sheet reconciliations prepared by two staff accountants for each January–June 2026 close, returned unsupported items with review notes and escalated unresolved balances to the controller.
Coordinated the assigned operating-expense close workstream; its controller-ready pack was submitted on business day six in January 2026 and day five in February–June, with controller sign-off tracked separately.
Investigated an unusual equipment-service invoice, documented the contract terms and proposed treatment under the existing accounting policy, then submitted the memo and proposed entry for controller approval.
Coached two staff accountants on linking support and writing reconciling-item explanations; in a June 2026 check of their 26 assigned reconciliations, 23 arrived with the required references and three were returned for completion.
Staff Accountant
Pinehaven Commercial Products · Charlotte, NC
July 2020–January 2024
Prepared cash, prepaid and accrued-expense reconciliations for assigned accounts at the April–December 2022 closes, recording explanations and supporting references for the senior accountant’s review.
Prepared the September 2023 operating-expense variance bridge explaining a $90,000 increase from August; separated timing items from changes in activity and sent unresolved explanations to the accounting manager.
Education
Bachelor of Science in Accounting · Fairhaven College · Charlotte, NC
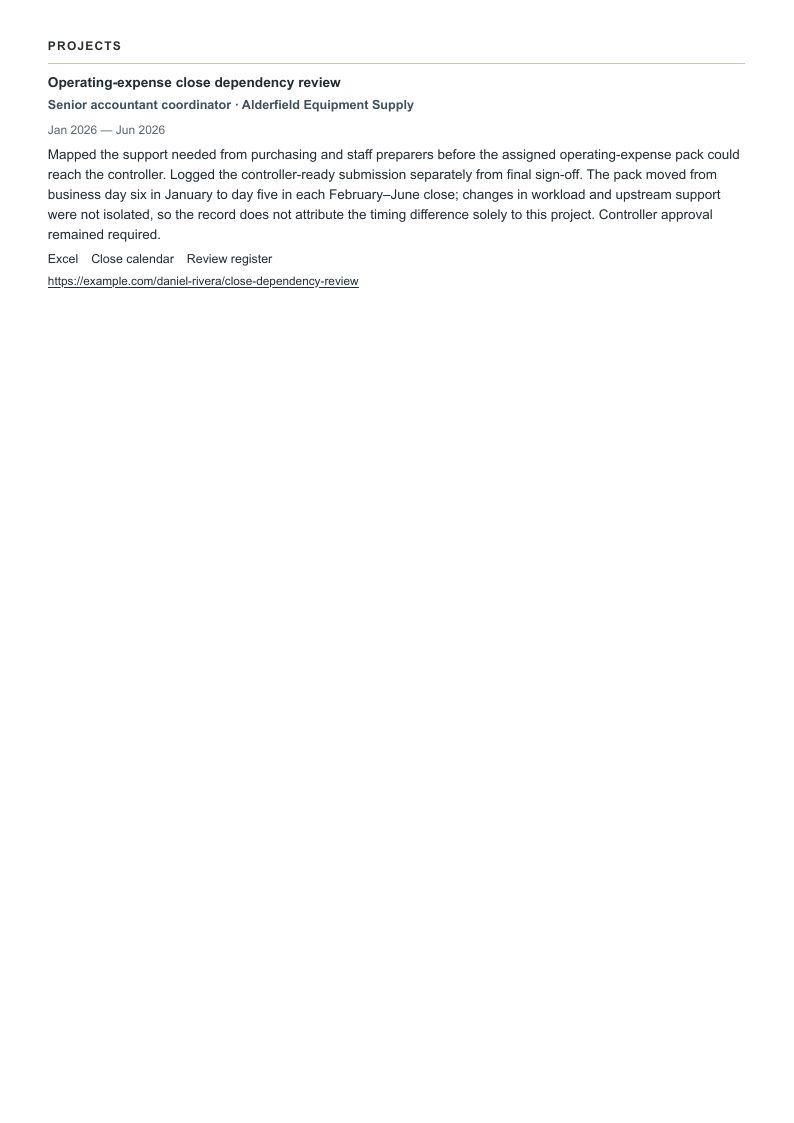
Mapped the support needed from purchasing and staff preparers before the assigned operating-expense pack could reach the controller. Logged the controller-ready submission separately from final sign-off. The pack moved from business day six in January to day five in each February–June close; changes in workload and upstream support were not isolated, so the record does not attribute the timing difference solely to this project. Controller approval remained required.
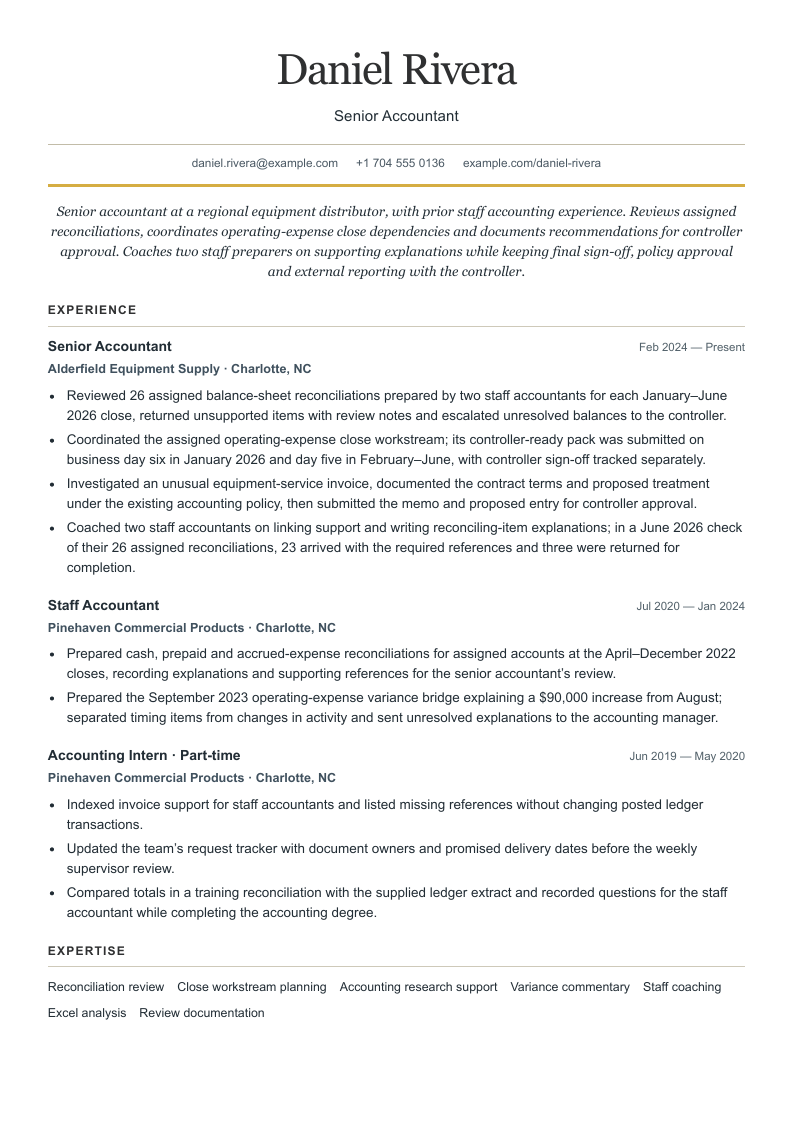
Review the expanded career record across all pages
This Ledger export has the photo off. The expanded record preserves every base field and adds an earlier part-time internship plus two projects: a review-note training guide and the earlier variance-bridge documentation. The internship runs alongside the degree and ends before the full-time staff job begins. We have not shortened the career to force a particular page count.
Senior accountant at a regional equipment distributor, with prior staff accounting experience. Reviews assigned reconciliations, coordinates operating-expense close dependencies and documents recommendations for controller approval. Coaches two staff preparers on supporting explanations while keeping final sign-off, policy approval and external reporting with the controller.
Skills
Reconciliation review · Close workstream planning · Accounting research support · Variance commentary · Staff coaching · Excel analysis · Review documentation
Experience
Senior Accountant
Alderfield Equipment Supply · Charlotte, NC
February 2024–Present
Reviewed 26 assigned balance-sheet reconciliations prepared by two staff accountants for each January–June 2026 close, returned unsupported items with review notes and escalated unresolved balances to the controller.
Coordinated the assigned operating-expense close workstream; its controller-ready pack was submitted on business day six in January 2026 and day five in February–June, with controller sign-off tracked separately.
Investigated an unusual equipment-service invoice, documented the contract terms and proposed treatment under the existing accounting policy, then submitted the memo and proposed entry for controller approval.
Coached two staff accountants on linking support and writing reconciling-item explanations; in a June 2026 check of their 26 assigned reconciliations, 23 arrived with the required references and three were returned for completion.
Staff Accountant
Pinehaven Commercial Products · Charlotte, NC
July 2020–January 2024
Prepared cash, prepaid and accrued-expense reconciliations for assigned accounts at the April–December 2022 closes, recording explanations and supporting references for the senior accountant’s review.
Prepared the September 2023 operating-expense variance bridge explaining a $90,000 increase from August; separated timing items from changes in activity and sent unresolved explanations to the accounting manager.
Accounting Intern · Part-time
Pinehaven Commercial Products · Charlotte, NC
June 2019–May 2020
Indexed invoice support for staff accountants and listed missing references without changing posted ledger transactions.
Updated the team’s request tracker with document owners and promised delivery dates before the weekly supervisor review.
Compared totals in a training reconciliation with the supplied ledger extract and recorded questions for the staff accountant while completing the accounting degree.
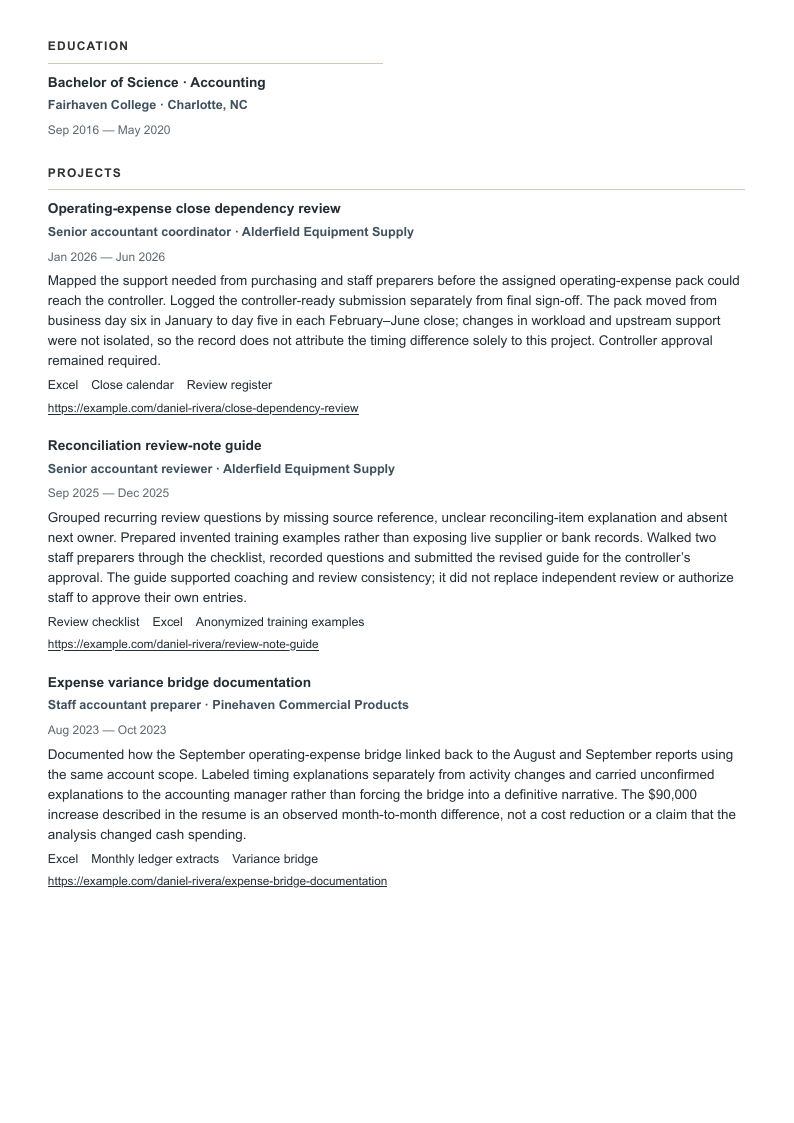
Education
Bachelor of Science in Accounting · Fairhaven College · Charlotte, NC
Mapped the support needed from purchasing and staff preparers before the assigned operating-expense pack could reach the controller. Logged the controller-ready submission separately from final sign-off. The pack moved from business day six in January to day five in each February–June close; changes in workload and upstream support were not isolated, so the record does not attribute the timing difference solely to this project. Controller approval remained required.
Review checklist · Excel · Anonymized training examples
Grouped recurring review questions by missing source reference, unclear reconciling-item explanation and absent next owner. Prepared invented training examples rather than exposing live supplier or bank records. Walked two staff preparers through the checklist, recorded questions and submitted the revised guide for the controller’s approval. The guide supported coaching and review consistency; it did not replace independent review or authorize staff to approve their own entries.
Documented how the September operating-expense bridge linked back to the August and September reports using the same account scope. Labeled timing explanations separately from activity changes and carried unconfirmed explanations to the accounting manager rather than forcing the bridge into a definitive narrative. The $90,000 increase described in the resume is an observed month-to-month difference, not a cost reduction or a claim that the analysis changed cash spending.
Check the review project’s final approval limitation, the earlier staff role and the end of the variance explanation. These details matter when a page break interrupts a long description. For your own application, keep extra work when it adds relevant evidence; use the exported pages to judge readability after editing rather than assuming more pages demonstrate more seniority.
Verify the exported record before submitting it
Read every page at normal size. Confirm the preparer and reviewer roles, controller limitations, close milestones, dates and final project sentences.
Copy the PDF text and inspect its order. Test portfolio and project links and compare the full email and phone with the original record.
Check the mathematics and measure names. Keep account-month counts separate from unique accounts, review completeness separate from accuracy and an expense movement separate from savings.
Follow the employer’s file instructions and inspect parsed titles, employers and dates after upload. No template guarantees a result in every hiring system.
The design buttons open signup with the selected template and photo preference. A free account is required; free-plan PDF downloads include a watermark. These previews show paid-plan output. Remove private workpapers, supplier details and account identifiers from any material you plan to share.
Questions, answered
Does a senior accountant have to manage people?
The title does not establish a reporting structure. Some roles include formal management, others include coaching and review without direct reports. Describe the actual relationship: who prepared the work, what you reviewed and which decisions remained with the manager or controller.
Can I include close improvements without claiming company-wide ownership?
Yes. Name the workstream, start and finish milestones, period and comparison. State whether you prepared, coordinated or approved the work. Track controller sign-off separately when your finish point is a reviewer-ready pack, and avoid assigning the whole team’s timing result to yourself.
How should I show readiness for a first senior role?
Keep your actual title and identify real review coverage, nonroutine investigations, dependency coordination or coaching. Give the duration and approval limits. If you have only prepared your own work, say so and assess whether the target vacancy fits that experience.
Can I list CPA because I completed an examination?
An examination result and an issued license are different. State your actual status and check the relevant jurisdiction before using the designation. The sample makes no CPA claim and cannot establish eligibility for a vacancy that requires a license.
Will a photo or template improve my screening results?
These previews demonstrate layout, not hiring outcomes. The default is without a photo for this US corporate example. Follow employer instructions, read all pages and inspect the uploaded record. The selected design and photo preference carry into signup; fictional candidate content does not.
Related accounting resume guides
Use the accountant resume guide for broader accounting contexts, or compare the staff accountant example for assigned preparation and review handoffs. Employers may use the titles differently; choose evidence by the work in the vacancy and preserve your true employment titles.
Sources and editorial scope
Resumize prepared this guide with AI-assisted research and drafting for English-language US private-sector corporate applications. Three primary employer descriptions were checked on October 27, 2026 and displayed Apply controls. Vacancy access, location rules and application status can change. The current Philz description, rather than an older search excerpt, supplies its stated Q1 2027 hybrid-return detail. CareerOneStop informs resume writing; BLS supplies occupational context. The fictional records, critiques and AI-generated portrait are original teaching examples, not employer endorsements or promises of hiring outcomes. This is resume advice, not financial, tax or legal instruction.
Checked October 27, 2026. Title: Senior Accountant; location label: Hybrid – San Francisco; Apply control present; no publication date displayed. Assigned operational areas, fluctuation analysis and cross-team process work illustrate one technology employer’s expectations; its location rules need separate checking.
Checked October 27, 2026. Title: Senior Accountant; location label: California – Los Angeles Market; Apply control present; no publication date displayed. The live description specifies Greater Los Angeles residence and a planned Q1 2027 hybrid return in Long Beach. Review, close coordination and staff development inform this guide; requirements are vacancy-specific.
Checked October 27, 2026. Title: Senior Accountant; location: New York, New York, United States; Apply control present; no publication date displayed. Its manager-reporting role includes initial analyst review alongside hands-on close work, showing that senior work can combine preparation and review.
US Department of Labor-sponsored career guidance on relevant job history, context and supported accomplishments. Used for resume writing, not technical accounting decisions.
Broad occupational and education context. CPA licensure is distinct from a job title or degree; the fictional candidate makes no CPA claim. Check vacancy requirements and the relevant jurisdiction before describing an actual credential.