A tax accountant resume should make the workpaper trail, reconciliation work and review responsibilities visible. Name the tax context and deliverable, separate unresolved differences from approved adjustments and show who reviews or files the result. This fictional in-house example uses six annotated rewrites and three actual designs without turning an accounting title into a license or representation authority.
These previews use the same layouts as the builder, with identical example content. Open a full preview to inspect the text and spacing.
Fictional candidate, employers, education and results. The optional portrait is AI-generated. Use your own evidence and photo; the example is not inserted into your resume.
Ledger
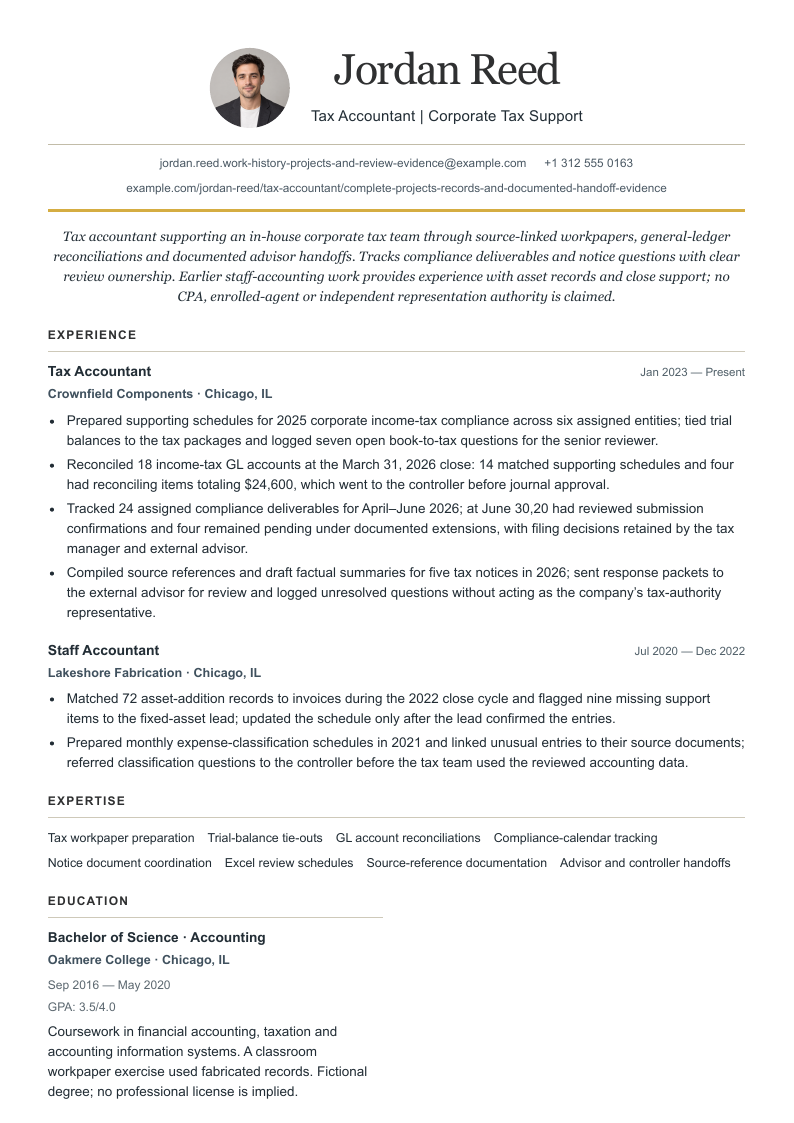
A centered serif identity, ruled contact strip and unheaded italic summary lead into Experience, Expertise, Education, optional Certifications and Projects. Gold rules provide restrained accents.
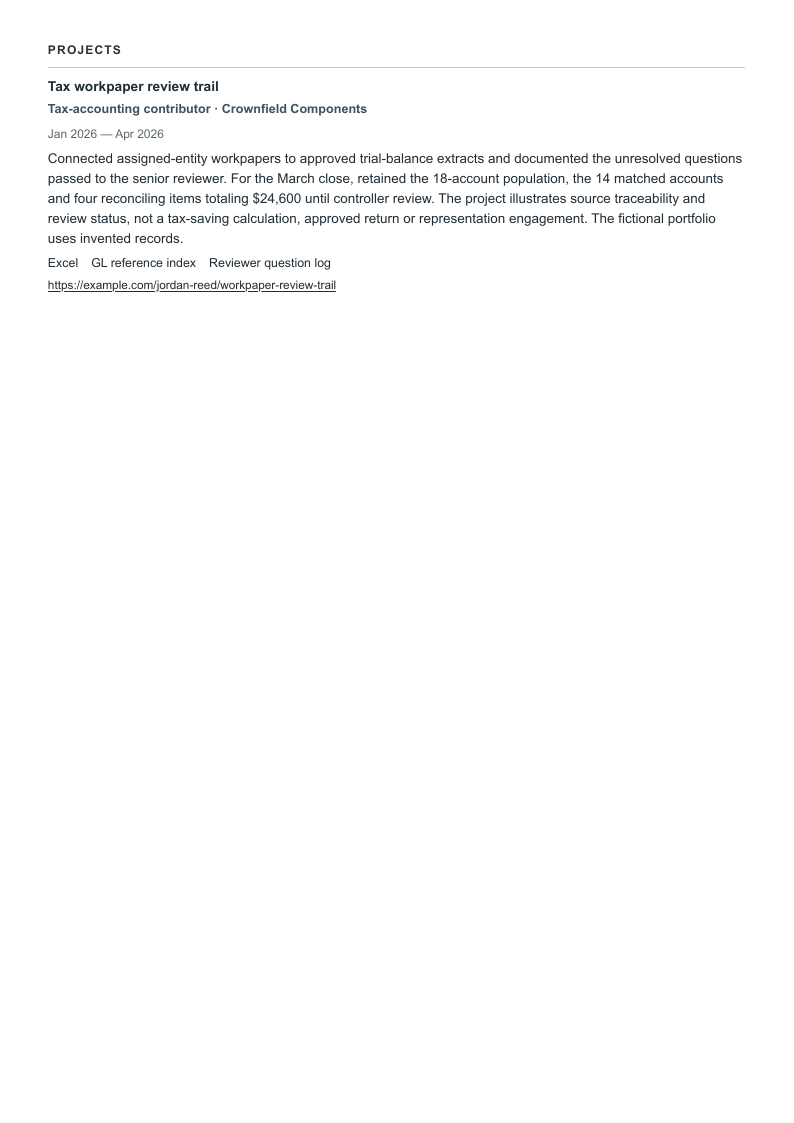
Before sending: The summary has no visible section label, and the project follows education. Inspect the dollar amount’s reconciliation context and complete final project sentences across all pages.
Original Professional uses a centered identity/contact block, then Professional Summary, Skills, Experience, Education, Projects and optional Certifications in one column. An optional circular portrait sits above the identity.
Before sending: Skills precede work history and social labels may shorten a URL. Check actual destinations, dates and the full education grade in your export.
A serif name and orange role accents introduce contact details before an unheaded summary, followed by Experience, Expertise, Education, optional Certifications and Projects in one column.
Before sending: Contacts sit above the summary, so inspect their complete endings as well as the workpaper review boundaries. Do not assume a quiet style guarantees application parsing.
“Use” opens signup with that design and photo preference selected for the builder. A free account is required. Free-plan PDF downloads include a watermark; see current plans for paid options. Photo conventions vary; follow the employer’s instructions and local expectations.
All three designs show the same fictional record. The default is without a photo; the optional portrait is AI-generated. Compare the full pages before choosing. The template buttons retain the exact design, photo choice and Tax Accountant role through signup. They do not insert the example career record or portrait into your account.
Jordan Reed is a fictional in-house tax accountant in Chicago. The current role supports corporate tax schedules, ledger reconciliations, a compliance calendar and advisor-reviewed notice packets. The earlier role is staff accounting. Every person, employer, degree, dollar amount, date and result is invented. The example.com links are placeholders, and the optional portrait is AI-generated. No CPA, enrolled-agent status or client representation is claimed.
Tax accountant supporting an in-house corporate tax team through source-linked workpapers, general-ledger reconciliations and documented advisor handoffs. Tracks compliance deliverables and notice questions with clear review ownership. Earlier staff-accounting work provides experience with asset records and close support; no CPA, enrolled-agent or independent representation authority is claimed.
Prepared supporting schedules for 2025 corporate income-tax compliance across six assigned entities; tied trial balances to the tax packages and logged seven open book-to-tax questions for the senior reviewer.
Reconciled 18 income-tax GL accounts at the March 31, 2026 close: 14 matched supporting schedules and four had reconciling items totaling $24,600, which went to the controller before journal approval.
Tracked 24 assigned compliance deliverables for April–June 2026; at June 30,20 had reviewed submission confirmations and four remained pending under documented extensions, with filing decisions retained by the tax manager and external advisor.
Compiled source references and draft factual summaries for five tax notices in 2026; sent response packets to the external advisor for review and logged unresolved questions without acting as the company’s tax-authority representative.
Staff Accountant
Lakeshore Fabrication · Chicago, IL
July 2020–December 2022
Matched 72 asset-addition records to invoices during the 2022 close cycle and flagged nine missing support items to the fixed-asset lead; updated the schedule only after the lead confirmed the entries.
Prepared monthly expense-classification schedules in 2021 and linked unusual entries to their source documents; referred classification questions to the controller before the tax team used the reviewed accounting data.
Education
Bachelor of Science in Accounting · Oakmere College · Chicago, IL
September 2016–May 2020
Coursework in financial accounting, taxation and accounting information systems. A classroom workpaper exercise used fabricated records. Fictional degree; no professional license is implied.
Excel · GL reference index · Reviewer question log
Connected assigned-entity workpapers to approved trial-balance extracts and documented the unresolved questions passed to the senior reviewer. For the March close, retained the 18-account population, the 14 matched accounts and four reconciling items totaling $24,600 until controller review. The project illustrates source traceability and review status, not a tax-saving calculation, approved return or representation engagement. The fictional portfolio uses invented records.
The record follows accounting information into reviewed tax support. It reports assigned entities, open questions, reconciling items and pending deliverables with their status intact. The degree and project are shown completely so you can compare the same facts in Ledger, original Professional and Plainspoken. These examples explain resume writing; they are not a calculation, filing instruction or personal tax advice.
Name the tax context and the deliverable you owned
Specify whether your work concerns corporate income tax, indirect tax, individual returns, provision support or another actual remit. Jordan prepares in-house corporate tax support and documents reviewer questions. That does not imply the authority to approve a tax position, sign a return, file for every jurisdiction or represent a taxpayer. Use verbs such as prepared, reconciled, researched or coordinated with enough context to identify the real contribution.
The three employer sources show why context matters. Box’s senior opening centers indirect tax, particularly sales and use tax and its connection to billing and other systems. HighLevel’s senior role supports corporate income-tax provision and compliance with internal and external partners. Brattle’s temporary global role spans ledger schedules, calendars, domestic/international filings and advisor coordination. These distinct scopes inform the guide without assigning all three to one fictional candidate.
A useful workpaper bullet identifies the assigned population, source data, check performed, unresolved question and reviewer. Jordan ties six entities’ schedules to trial balances and passes seven questions onward. A statement such as “handled all taxes” would hide the assignment and the review. If you actually own a final decision or a wider remit, state the responsibility and the relevant credential or authority accurately rather than leaving the reader to infer it.
Keep the boundary between accounting data and a tax conclusion visible. An asset invoice check can improve a schedule’s traceability without establishing final tax treatment. A ledger difference can be a timing or classification matter that needs review, rather than a recoverable overpayment. A notice packet can show coordination without implying that its compiler approved the response position or acted as a representative.
Six tax accountant rewrites with reasoning
Each after sentence appears verbatim in the base resume. The before statements are deliberately weak or overstated examples, not additional facts. Use the evidence prompts to check your own record, and replace invented sample figures with results you can substantiate and share.
1. Name the deliverable and review boundary
Before: Prepared all company taxes flawlessly.
After: Prepared supporting schedules for 2025 corporate income-tax compliance across six assigned entities; tied trial balances to the tax packages and logged seven open book-to-tax questions for the senior reviewer.
Why it works: Six entities define the assigned scope; seven questions remain open for review. Supporting schedules are not independently approved returns, and a preparation step does not prove flawless compliance.
Evidence to check: Assigned-entity list, approved trial-balance extracts, workpaper references, open-question log and reviewer sign-off.
2. Distinguish reconciliation differences from savings
Before: Saved $24,600 by finding tax errors.
After: Reconciled 18 income-tax GL accounts at the March 31, 2026 close: 14 matched supporting schedules and four had reconciling items totaling $24,600, which went to the controller before journal approval.
Why it works: The account statuses reconcile to 18. The $24,600 is an aggregate difference awaiting review, not tax saved, recovered cash, an error determination or an approved adjustment.
Evidence to check: Account population, supporting balances, reconciling-item register, cutoff and controller review record.
3. Keep pending deliverables visible
Before: Guaranteed every filing was on time.
After: Tracked 24 assigned compliance deliverables for April–June 2026; at June 30,20 had reviewed submission confirmations and four remained pending under documented extensions, with filing decisions retained by the tax manager and external advisor.
Why it works: States the cohort and status at a cutoff without a blanket timeliness guarantee. The manager and advisor control filing decisions; pending items are not silently treated as completed.
Evidence to check: Compliance calendar, applicable reviewed dates, extension records, confirmations and responsibility matrix.
4. Show notice support without implying representation
Before: Represented the company before every tax authority.
After: Compiled source references and draft factual summaries for five tax notices in 2026; sent response packets to the external advisor for review and logged unresolved questions without acting as the company’s tax-authority representative.
Why it works: Five notice packets show a defined coordination workload. Collecting facts and organizing drafts are distinct from approving a position, signing a response or exercising representation authority.
Evidence to check: Notice register, permitted document index, advisor handoff and the approved response owner.
5. Use an earlier accounting foundation
Before: Determined every asset’s tax treatment as a staff accountant.
After: Matched 72 asset-addition records to invoices during the 2022 close cycle and flagged nine missing support items to the fixed-asset lead; updated the schedule only after the lead confirmed the entries.
Why it works: The count describes an accounting-record review, not 72 assets with final tax classifications. Nine gaps are questions raised, and the lead retains approval.
Evidence to check: Asset-addition population, source-invoice checklist, missing-support log and approved schedule revision.
6. Describe the information you prepared
Before: Approved all deductions and eliminated audit risk.
After: Prepared monthly expense-classification schedules in 2021 and linked unusual entries to their source documents; referred classification questions to the controller before the tax team used the reviewed accounting data.
Why it works: Shows traceable input into tax work without turning bookkeeping classifications into tax-deduction decisions. Reviewed data does not establish eliminated audit risk.
Evidence to check: Schedule versions, source references, controller questions and the tax-team data handoff.
Use numbers that describe the work accurately
The summary should preview the evidence below it. Jordan names source-linked workpapers, GL reconciliations and advisor handoffs, supported by specific examples. It does not promise tax savings or error-free compliance. Choose the systems and tax context you can substantiate, and match them to the vacancy instead of adding every tax area from a search result.
At the March 31, 2026 close, the example covers 18 income-tax GL accounts: 14 match supporting schedules and four have reconciling items totaling $24,600. That amount describes differences passed to the controller before journal approval. It is not a reduction in tax liability, recovered cash, an approved adjustment or a proven error. A precise reconciliation can be valuable evidence without a savings claim.
The compliance-calendar example follows 24 assigned deliverables for April–June 2026. At June 30,20 have reviewed submission confirmations and four remain pending under documented extensions. The record preserves the pending status and the manager/advisor decision boundary. It does not establish that every statutory deadline across the organization was met. If you report timeliness in your own resume, define the population, reviewed dates, exclusions and completion evidence.
Use the relevant document and period with every claim. Six entities,18 accounts,24 deliverables and five notices are different populations and cannot be added into one productivity figure. A before-and-after comparison needs a consistent definition and a credible baseline. When a publishable metric is unavailable, explain a source-linked review, a difficult reconciliation or a clearer handoff without inventing a percentage.
Connect tax-accounting skills to reviewed work
A skill should point to a record, method or deliverable you can discuss. Excel matters here because schedules reconcile and retain source references; the software name alone does not demonstrate tax judgment. Describe systems you actually used, keep review ownership explicit and use permitted aggregates or fabricated examples for public work samples.
Tax Accountant skills and supporting evidence
Skill
Evidence to gather
Fictional example
Workpaper preparation
Assigned entity scope, source references and reviewer questions.
Six entity packages retain seven open questions.
GL reconciliation
Account population, cutoff, support and item status.
18 accounts split into 14 matched and four for review.
Compliance tracking
Reviewed dates, confirmations, extensions and next owner.
24 deliverables retain four pending items at June 30.
Notice coordination
Source index, factual summary and response owner.
Five packets go to the external advisor for review.
Excel documentation
Versioned schedules and traceable supporting totals.
A review trail connects extracts to reconciling items.
Cross-functional communication
A question and documented decision handoff.
Controller approval precedes schedule or journal changes.
Separate the degree, professional status and job duties
List your actual degree, field, institution and dates. Jordan’s fictional accounting degree includes relevant coursework and GPA 3.5/4.0. GPA is optional; a more experienced applicant may prioritize current work. The included grade remains part of the preview record, rather than disappearing because one design places qualifications differently.
Professional status needs its own accurate description. The IRS distinguishes state-issued CPA licensing, IRS enrolled-agent status and other preparer qualifications. An accounting degree, tax-accountant title or course completion does not establish those credentials or representation rights. Jordan claims no credential. If you hold one, state its exact current status and jurisdiction where applicable, and verify the issuer’s record before publishing it.
PTIN requirements concern particular preparation activities and have exceptions. The IRS FAQ explicitly distinguishes an employee preparing the employer’s own returns from paid preparation of outside returns. Do not treat PTIN as a substitute for a CPA/EA credential or infer that every tax-accountant role has the same requirements. This example describes in-house schedules and advisor support; check current IRS and applicable state guidance for your actual duties.
The workpaper project adds the source index and review trail behind the experience. It preserves the 18-account population and the difference’s unresolved status until review. A public portfolio can use invented records or an approved blank structure. It should not publish taxpayer identifiers, actual returns, confidential balances, notices or account access merely to make a resume look more concrete.
Show the accounting foundation without inflating authority
An earlier staff-accounting role can support a move into tax through reconciliations, source checks, schedules and reliable close handoffs. Keep the actual title and explain what the tax team received. Jordan’s asset-record and expense-schedule work shows traceable inputs, while the fixed-asset lead and controller retain approval. It does not retroactively establish tax-return ownership.
For a first tax-accounting application, describe a supervised workpaper, class exercise or relevant internship accurately. Name the source records, the reconciliation or research task and the reviewer. Label fabricated data and academic work. A coursework case is not a real taxpayer engagement, and completing a simulated return does not establish a professional credential or permission to represent anyone.
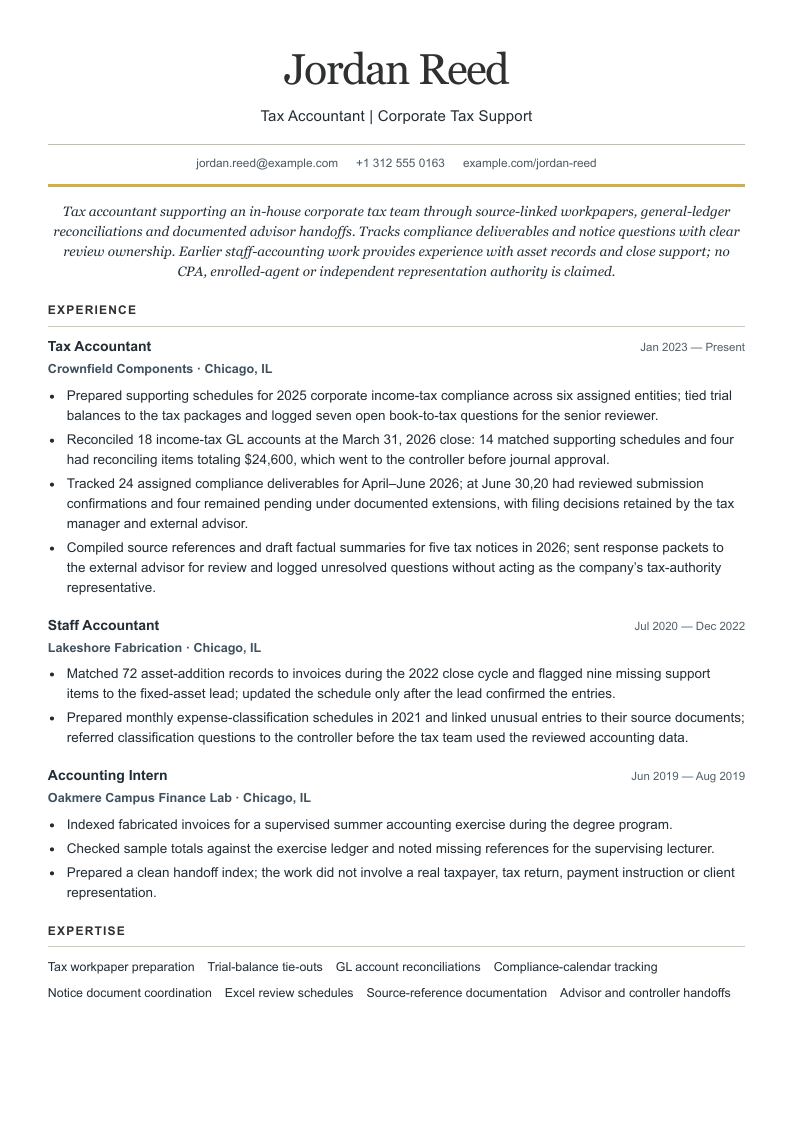
The expanded June–August 2019 campus internship overlaps Jordan’s degree and precedes the July 2020 staff-accounting job. It uses invented invoices and a sample ledger under a lecturer’s supervision. A candidate with real client-facing work should instead describe the actual assignment and permitted responsibilities, retaining any approval and authority boundaries required by that work.
Inspect long contacts with the optional photo
The Ledger long-contact export has the photo on and changes only Jordan’s resume email and portfolio URL. User identity, phone, jobs, dollar amount, degree, GPA and projects remain identical. Inspect the full email and final URL segment against the accessible record, then verify the PDF link destination. The original Professional design may shorten a social label while preserving the full destination.
Tax accountant supporting an in-house corporate tax team through source-linked workpapers, general-ledger reconciliations and documented advisor handoffs. Tracks compliance deliverables and notice questions with clear review ownership. Earlier staff-accounting work provides experience with asset records and close support; no CPA, enrolled-agent or independent representation authority is claimed.
Prepared supporting schedules for 2025 corporate income-tax compliance across six assigned entities; tied trial balances to the tax packages and logged seven open book-to-tax questions for the senior reviewer.
Reconciled 18 income-tax GL accounts at the March 31, 2026 close: 14 matched supporting schedules and four had reconciling items totaling $24,600, which went to the controller before journal approval.
Tracked 24 assigned compliance deliverables for April–June 2026; at June 30,20 had reviewed submission confirmations and four remained pending under documented extensions, with filing decisions retained by the tax manager and external advisor.
Compiled source references and draft factual summaries for five tax notices in 2026; sent response packets to the external advisor for review and logged unresolved questions without acting as the company’s tax-authority representative.
Staff Accountant
Lakeshore Fabrication · Chicago, IL
July 2020–December 2022
Matched 72 asset-addition records to invoices during the 2022 close cycle and flagged nine missing support items to the fixed-asset lead; updated the schedule only after the lead confirmed the entries.
Prepared monthly expense-classification schedules in 2021 and linked unusual entries to their source documents; referred classification questions to the controller before the tax team used the reviewed accounting data.
Education
Bachelor of Science in Accounting · Oakmere College · Chicago, IL
September 2016–May 2020
Coursework in financial accounting, taxation and accounting information systems. A classroom workpaper exercise used fabricated records. Fictional degree; no professional license is implied.
Excel · GL reference index · Reviewer question log
Connected assigned-entity workpapers to approved trial-balance extracts and documented the unresolved questions passed to the senior reviewer. For the March close, retained the 18-account population, the 14 matched accounts and four reconciling items totaling $24,600 until controller review. The project illustrates source traceability and review status, not a tax-saving calculation, approved return or representation engagement. The fictional portfolio uses invented records.
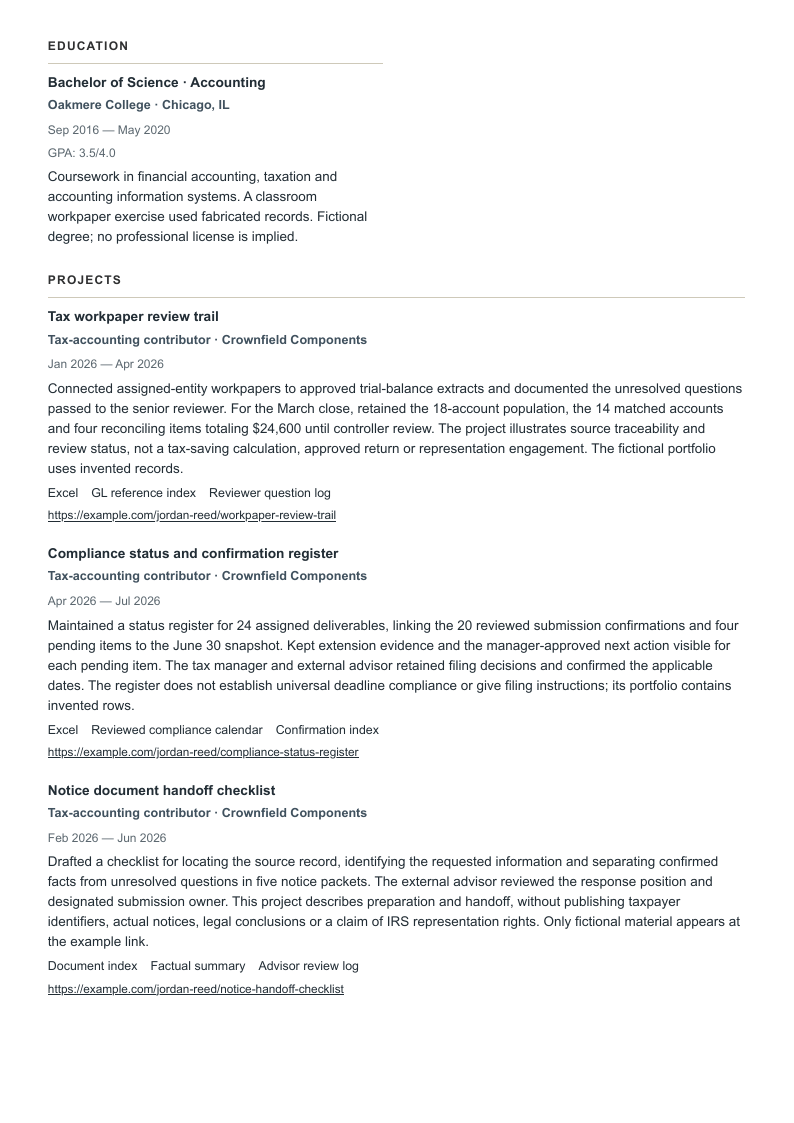
The expanded Ledger record has the photo off and preserves the base record. It adds the supervised campus internship, a compliance-status register and a notice-handoff checklist. The additions explain existing deliverable and notice counts without adding tax-saving or authority claims. They test how a longer record flows; they do not mean that every applicant needs a fixed number of pages.
Tax accountant supporting an in-house corporate tax team through source-linked workpapers, general-ledger reconciliations and documented advisor handoffs. Tracks compliance deliverables and notice questions with clear review ownership. Earlier staff-accounting work provides experience with asset records and close support; no CPA, enrolled-agent or independent representation authority is claimed.
Prepared supporting schedules for 2025 corporate income-tax compliance across six assigned entities; tied trial balances to the tax packages and logged seven open book-to-tax questions for the senior reviewer.
Reconciled 18 income-tax GL accounts at the March 31, 2026 close: 14 matched supporting schedules and four had reconciling items totaling $24,600, which went to the controller before journal approval.
Tracked 24 assigned compliance deliverables for April–June 2026; at June 30,20 had reviewed submission confirmations and four remained pending under documented extensions, with filing decisions retained by the tax manager and external advisor.
Compiled source references and draft factual summaries for five tax notices in 2026; sent response packets to the external advisor for review and logged unresolved questions without acting as the company’s tax-authority representative.
Staff Accountant
Lakeshore Fabrication · Chicago, IL
July 2020–December 2022
Matched 72 asset-addition records to invoices during the 2022 close cycle and flagged nine missing support items to the fixed-asset lead; updated the schedule only after the lead confirmed the entries.
Prepared monthly expense-classification schedules in 2021 and linked unusual entries to their source documents; referred classification questions to the controller before the tax team used the reviewed accounting data.
Accounting Intern
Oakmere Campus Finance Lab · Chicago, IL
June 2019–August 2019
Indexed fabricated invoices for a supervised summer accounting exercise during the degree program.
Checked sample totals against the exercise ledger and noted missing references for the supervising lecturer.
Prepared a clean handoff index; the work did not involve a real taxpayer, tax return, payment instruction or client representation.
Education
Bachelor of Science in Accounting · Oakmere College · Chicago, IL
September 2016–May 2020
Coursework in financial accounting, taxation and accounting information systems. A classroom workpaper exercise used fabricated records. Fictional degree; no professional license is implied.
Excel · GL reference index · Reviewer question log
Connected assigned-entity workpapers to approved trial-balance extracts and documented the unresolved questions passed to the senior reviewer. For the March close, retained the 18-account population, the 14 matched accounts and four reconciling items totaling $24,600 until controller review. The project illustrates source traceability and review status, not a tax-saving calculation, approved return or representation engagement. The fictional portfolio uses invented records.
Excel · Reviewed compliance calendar · Confirmation index
Maintained a status register for 24 assigned deliverables, linking the 20 reviewed submission confirmations and four pending items to the June 30 snapshot. Kept extension evidence and the manager-approved next action visible for each pending item. The tax manager and external advisor retained filing decisions and confirmed the applicable dates. The register does not establish universal deadline compliance or give filing instructions; its portfolio contains invented rows.
Document index · Factual summary · Advisor review log
Drafted a checklist for locating the source record, identifying the requested information and separating confirmed facts from unresolved questions in five notice packets. The external advisor reviewed the response position and designated submission owner. This project describes preparation and handoff, without publishing taxpayer identifiers, actual notices, legal conclusions or a claim of IRS representation rights. Only fictional material appears at the example link.
Read through each final sentence, particularly the distinction between a pending deliverable and a completed filing, and between a factual notice packet and representation. Ledger places Projects after qualifications. Plainspoken places contacts before the summary, while Professional places Skills before Experience. Review the actual export and copied text in addition to the visual layout.
Check the file you will submit
Check scope and ownership. Keep preparation, reconciliation, review, approval, filing and representation distinct. Use professional titles and credentials only in their actual current form.
Reconcile counts and money. Retain the period, population and cutoff. A reconciling difference is not automatically tax saved, an error or recovered cash.
Inspect the entire export. Verify contact endings, dates, education grade, project roles and final review qualifiers. Check contacts above Plainspoken’s summary and full destinations behind shortened Professional labels.
Follow application instructions. Open permitted links, copy PDF text and inspect parsed fields. Use the requested file type. No layout guarantees parsing, an interview, compliance or a job offer.
A free account is required for the builder. Free-plan PDF downloads include a watermark; these images show paid-plan output. Use buttons carry your chosen design, photo preference and Tax Accountant role into signup without copying the fictional example into your account.
Name the actual tax context and show workpapers, source checks, reconciliations, calendar follow-through or other relevant work. Identify the assigned scope and reviewer instead of claiming all tax responsibilities from a job title.
Can I call a reconciling difference tax savings?
Use the result’s actual status. The fictional $24,600 is an aggregate GL reconciliation difference passed to the controller before approval. It is not approved tax savings, an overpayment recovery or a final error determination.
Does an accounting degree mean I can use CPA or EA?
No such status follows from the degree or job title. The IRS distinguishes CPA licensing and enrolled-agent status from other qualifications. State only a credential you actually hold, with its accurate current status; this example claims neither.
Does every tax accountant need a PTIN?
Requirements depend on duties and exceptions. The IRS FAQ distinguishes in-house employees preparing their employer’s own returns from outside compensated preparation. Check current IRS and applicable state guidance; a PTIN is not a professional license or blanket representation authority.
How can a staff accountant show relevant tax experience?
Describe the actual schedules, source checks, reconciliations and tax-team handoffs you performed. Keep the real title and approval owner. Do not convert an accounting classification or classroom exercise into an independently approved tax position.
What does choosing a template preserve?
The signup button retains the exact Ledger, Professional or Plainspoken design, photo preference and Tax Accountant role. It does not copy Jordan’s fictional resume or AI portrait. A free account is required; free-plan PDF downloads include a watermark.
Prepared by Resumize with AI-assisted research and drafting for English-language US applications. Box, HighLevel and The Brattle Group descriptions were retrieved directly with full responsibilities and application controls on October 28, 2026. Their senior indirect-tax, corporate-income-tax and temporary global scopes are distinct; they do not define one universal tax-accountant remit. Current IRS credentials and PTIN guidance support the limited qualification distinctions here. This is resume advice, not personal tax advice or a determination of anyone’s filing or representation rights. All career facts, amounts and rewrites are original fiction, with an AI-generated optional portrait and placeholder links. CareerOneStop supplies general writing and formatting advice, not a test of these designs. No application was submitted and no tax, screening or hiring outcome is promised.
Retrieved October 28, 2026: Chicago, IL, United States; full description and inline application form available, no posting date displayed. Senior indirect-tax example covers sales/use tax, billing systems and cross-functional work. Its senior and indirect-tax remit differs from this fictional corporate-income-tax support sample.
Retrieved October 28, 2026: United States, Remote; full description and Apply for this job link available, no posting date shown. Corporate-income-tax role covers provision/compliance workpapers, reconciliations and external partners. CPA or a tax master’s is a plus in this posting; that does not confer a credential on the sample candidate.
Retrieved October 28, 2026: Boston, MA, United States; full description and application form available, no posting date displayed. Temporary role spans domestic/international filings, ledger schedules, calendars and local-advisor coordination. Its global indirect-tax duties are not imported wholesale into this US resume example.
Read October 28, 2026. Distinguishes preparer qualifications and representation rights, including state-issued CPA licensing and IRS enrolled-agent status. Used only to avoid equating a degree or tax-accountant job title with a credential or authority; no personal tax advice is provided.
Read October 28, 2026 through the web reader. Explains PTIN requirements and exceptions for particular preparation duties. A PTIN is not presented as a CPA/EA credential or blanket representation authority. This fictional record describes in-house workpaper and advisor support, not paid preparation for outside clients.
Read October 28, 2026. US Department of Labor-sponsored guidance on relevant work context, employment dates and specific contributions. All sample achievements and rewrites here are original fiction.
Read October 28, 2026. General advice favors clear, consistent presentation and a simple single-column starting point. It does not test or endorse these designs; check your own export and application fields.